

Overview
Capstone treats options as a weekly operating process rather than a stream of isolated trade ideas. The sequence is simple and repeatable: confirm the contract terms, reject poor liquidity, choose an expiry that fits the intended holding period, check whether implied volatility looks relatively rich or cheap for the structure being considered, select from a short list of simple strategies, then manage the position with pre-written exit rules.
This matters because exchange-listed options are standardised contracts, but the details still shape the real risk. Style, settlement method, multiplier, strike and expiry determine what the position costs, what it can become, and what can happen at expiration or assignment.
In practice, a useful playbook is less about prediction and more about fit. A covered call can fit a stock holder who is willing to sell at a chosen price. A debit spread can fit a directional view with capped risk. A cash-secured put can fit a willingness to buy stock at an effective discount. A small menu with clear rules is often more repeatable than a large strategy catalogue.
Scope and assumptions
This article is framed around U.S. listed options because the approved sources are U.S. venue and regulator materials. Where product-specific details can vary, the discussion stays with points that are common across the cited sources.
The playbook is educational and operational in tone. It focuses on process: contract mechanics, liquidity, time, volatility, strategy fit, and trade management.
Exact broker cut-offs, exercise procedures and product terms can vary. That is why the playbook favours simple, earlier management rules rather than relying on last-minute expiration handling.
Main narrative
Start with the contract, not the chart
Before thinking about direction, confirm the underlying, strike, expiry, contract multiplier, style and settlement. For standard U.S. equity options, one contract generally represents 100 shares and premium is quoted on a per-share basis, so one point of premium equals $100 per contract. U.S. equity options are generally American-style, which means they may be exercised before expiry. Some index options are European-style, meaning they are exercisable only on expiration.
This first step keeps the trade grounded in what the contract can actually do. The same quoted premium can imply very different outcomes depending on multiplier and settlement.
Translate premium into cash terms
A quoted premium is not yet the real cash amount. If an option is quoted at 2.40 and the multiplier is 100, one long contract costs $240 before fees and one short contract collects $240 before fees. That premium is the cash paid or received, not the full notional exposure behind the contract.
This distinction is important because the premium can look small while the resulting stock obligation is much larger.
Check what exercise or assignment could create
A long equity call that is exercised creates a stock purchase at the strike price for 100 shares per contract. A short equity call that is assigned creates an obligation to deliver 100 shares per contract at the strike. A short put that is assigned creates an obligation to buy 100 shares per contract at the strike.
This is one of the simplest but most useful questions in options trading: if this contract is exercised or assigned, what stock or cash position appears next?
Reject poor liquidity early
Liquidity should be screened before strategy selection. The first check is usually the bid-ask spread. A tighter spread tends to support better execution quality. Displayed size matters too, as does order handling. Volume and open interest are useful context, but they do not guarantee liquidity. Open interest is simply the number of outstanding contracts.
A practical way to think about spread cost is to compare the spread with the premium itself. A 0.10 spread on a 0.20 option is heavy friction. The same 0.10 spread on a 10.00 option is much smaller in percentage terms. When price control matters, limit orders are generally more suitable than market orders.
Match expiry to the holding period
Days to expiry shape flexibility and time decay. Theta is not linear and tends to accelerate as expiration approaches, particularly in shorter-dated options and especially around at-the-money contracts. That means short-dated long options need the underlying move to happen sooner, while short-premium positions may benefit from faster decay but can face sharper late-stage risk if price moves through the strikes.
Longer-dated options require more premium but give the idea more time to work. So the question is not simply which expiry is cheapest, but which expiry fits the intended holding window.
Use volatility as a filter, not a shortcut
Implied volatility is derived from current option prices and reflects current market expectations. Realised volatility is based on past price movement. At a high level, richer implied volatility usually means options are priced more expensively relative to calmer conditions, while lower implied volatility means they are priced more cheaply.
This does not decide market direction, but it can help with structure selection. When implied volatility is elevated relative to the recent environment, premium-selling structures may look more attractive if risk is defined and liquidity is adequate. When implied volatility is subdued, debit structures can be relatively cheaper. This is a selection tool, not a guarantee.
Keep the strategy menu small
A simple playbook does not need every options structure.
- Covered call: suitable when stock is already owned and the holder is willing to sell at the strike. Premium is received, but upside is capped.
- Cash-secured put: suitable when the goal is to buy stock lower and the trader is willing and able to purchase shares if assigned.
- Long call or long put: suitable for a directional view with risk limited to premium paid, while time decay works against the holder.
- Debit spread: suitable for a directional view with defined risk and a lower premium outlay than an outright long option, in exchange for capped upside.
- Credit spread: suitable for premium selling with defined risk, while still requiring care around assignment and expiry.
A useful simplification is to match structure to objective. If the goal is stock plus income, think covered call. If the goal is stock entry lower, think cash-secured put. If the goal is pure direction, choose between an outright long option and a debit spread. If the goal is selling premium, a basic playbook can favour defined-risk credit spreads over undefined-risk naked selling.
Write the exit rule before entry
Each trade should start with a written plan for profit-taking, maximum acceptable loss, latest hold date, and whether the position may be held into expiry. This matters because options often change character near expiration. Theta accelerates, short American-style equity options can still be assigned, and in-the-money expiring contracts are commonly subject to automatic exercise procedures unless contrary instructions are given through the clearing chain.
The cleanest beginner rule is usually not to rely on expiration handling as the main exit method.
A weekly operating loop
A practical weekly checklist can look like this:
- Confirm underlying, strike, expiry, multiplier, style and settlement.
- Convert premium into actual cash paid or received.
- Confirm what exercise or assignment could create in stock or cash terms.
- Check bid-ask spread first, then displayed size, then volume and open interest.
- Choose days to expiry that match the intended holding period.
- Note whether implied volatility looks relatively rich or cheap at a high level.
- Select the simplest structure that matches the objective.
- Enter only with a pre-written profit, loss and time-based exit rule.
The strength of the playbook is not complexity. It is consistency.
Worked example: covered call
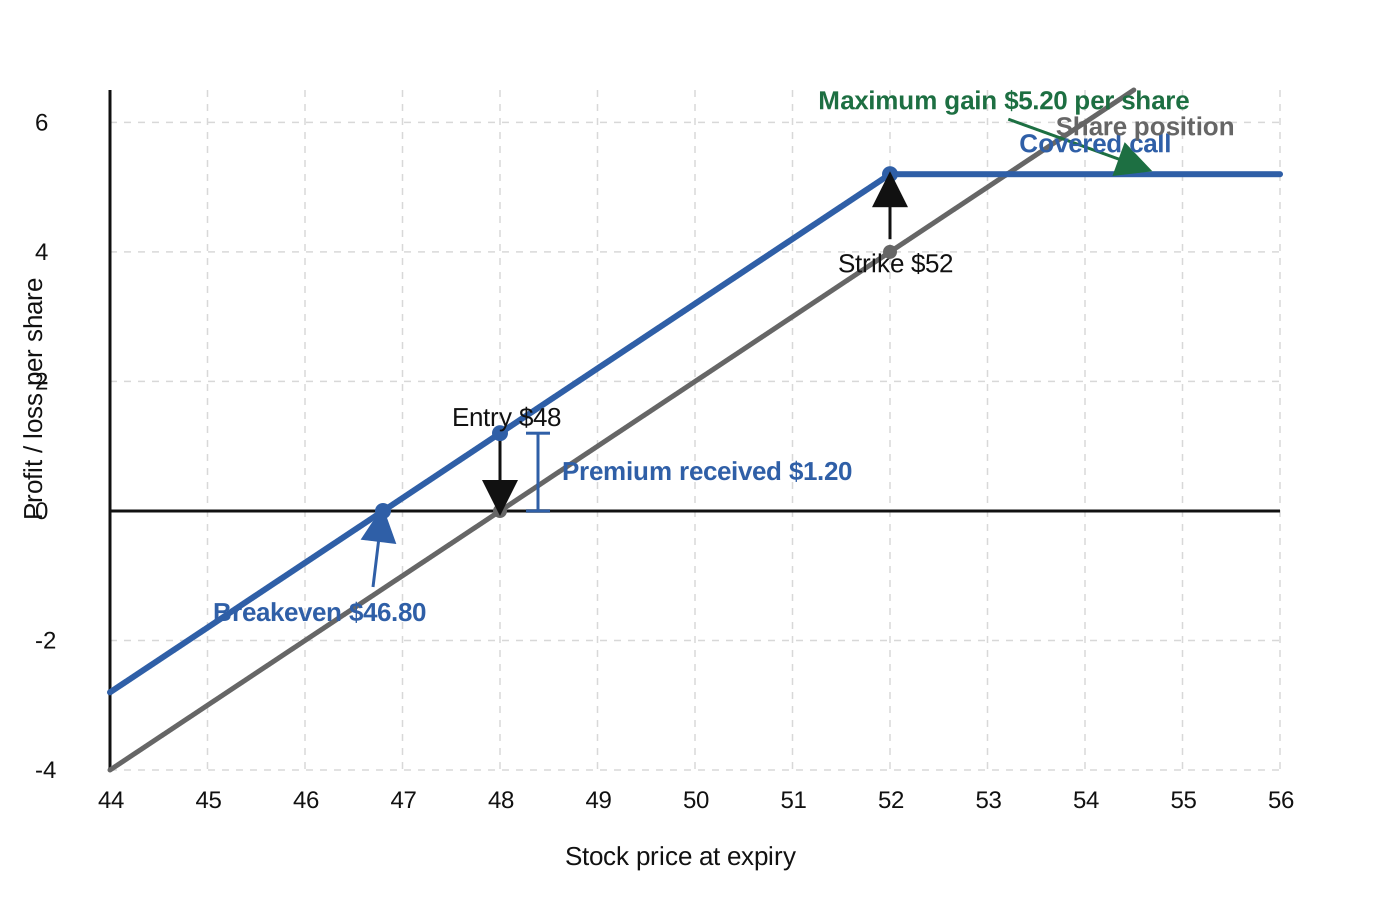
Assume an investor owns 100 shares of XYZ at $48 and sells one 52 call expiring in 21 days for 1.20. With a 100 multiplier, the premium received is $120 before fees.
At entry:
- Share position value: $4,800
- Short call premium received: $120
- Gross covered call basis net of premium: $4,680
After 10 days, suppose XYZ is still $48 and the 52 call has fallen from 1.20 to 0.55 because time has passed and the option remains out of the money. The unrealised gain on the short call is 0.65, or $65. This is the basic effect of time decay on an out-of-the-money short option when other factors are broadly steady.
If XYZ closes at $50 at expiry, the 52 call expires out of the money, the shares remain in the account, the $120 premium is kept, and the stock shows a $200 unrealised gain versus the original $48 cost. Total gross position gain at expiry versus original stock cost is $320.
If XYZ closes at $55 at expiry, the 52 call finishes in the money. If it is held through expiry and assigned, the shares are sold at $52. The stock gain realised is $400 and the option premium kept is $120, for a total gross gain of $520. The trade-off is clear: gains above $52 are given up because the covered call caps the upside.
The lesson is simple. A covered call fits when income and a pre-accepted sale price matter more than unlimited upside.
Worked example: defined-risk debit spread
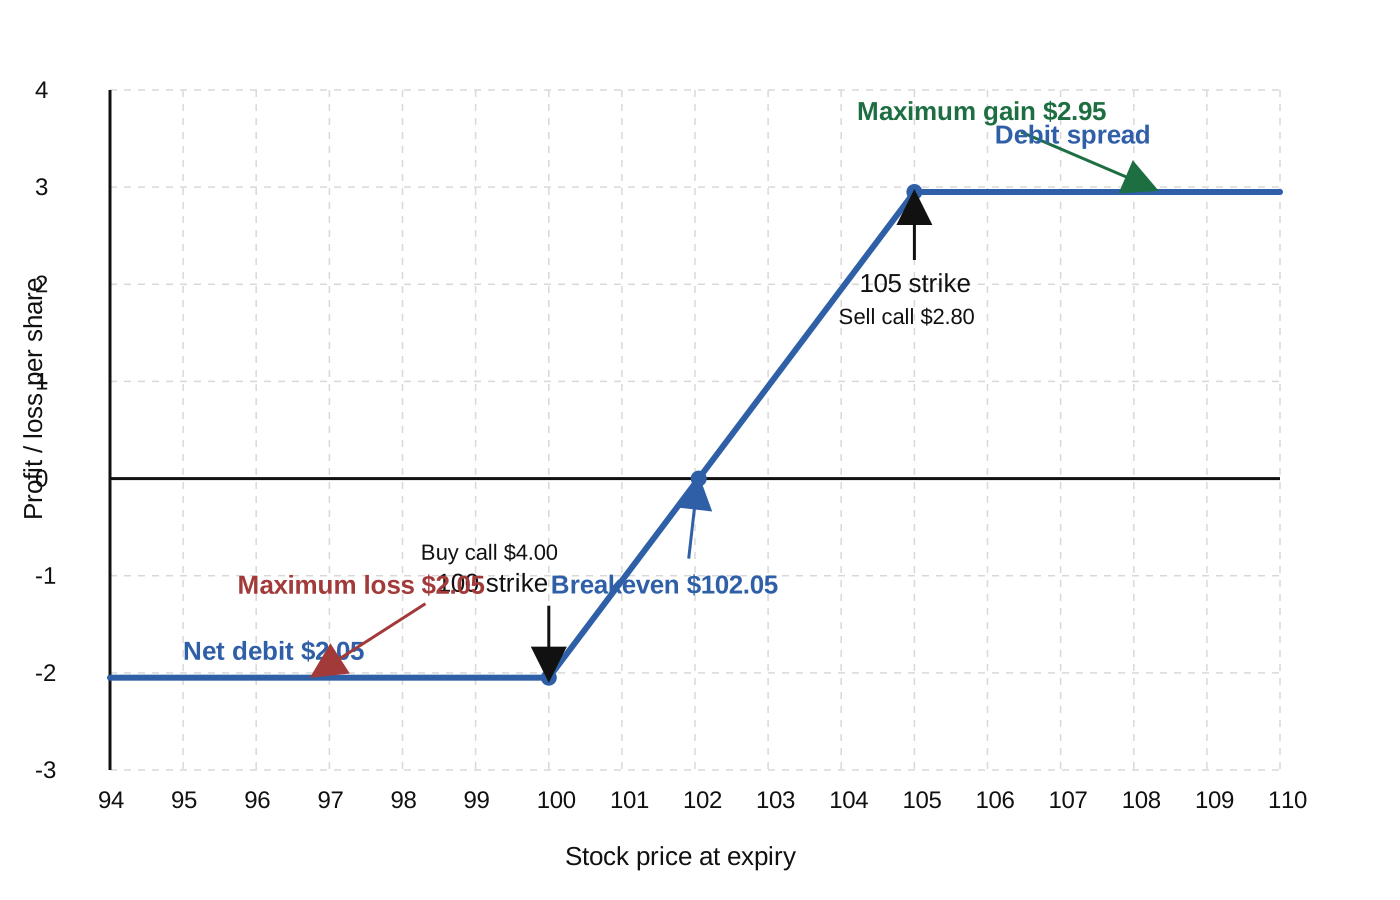
Assume XYZ shares trade at $100 and the view is moderately bullish over the next month. Compare two call options with the same expiry in 35 days:
- Long 100 call at 4.20 ask and 4.00 bid
- Short 105 call at 2.10 bid and 2.25 ask
Using a 100/105 long call debit spread entered at a net debit of 2.05 with a limit order, the net cost is $205 before fees with a 100 multiplier. The maximum value at expiry if fully in the money is the 5-point width of the spread. Maximum profit is therefore $295 and maximum loss is $205.
Why choose the spread? An outright long 100 call would cost about $420. The spread costs about $205, roughly halving premium outlay in exchange for capping upside above $105. That fits a modest rather than explosive bullish view.
The liquidity check still matters. Here the spreads on the individual legs are acceptable relative to premium, and 35 days leaves time for the move without immediately entering the fastest phase of decay. A limit order helps control execution.
A written management plan might include profit-taking if the spread reaches roughly 70 to 80 per cent of maximum value before expiry, a loss rule if the thesis breaks or the spread loses about 40 to 50 per cent from entry, and a time rule to reduce or exit if the move has not happened by around 10 days to expiry. Avoiding expiry can matter because spread positions can still create risk if the protective leg is not exercised or otherwise acted upon.
If XYZ rises to $104 with 14 days left and the spread marks at 3.40, the position is worth $340. Closing there would produce a gross profit of $135 and remove remaining time and exercise risk.
For a basic options process, simplicity is a strength. Fewer structures, clearer contract checks, better liquidity discipline and earlier exit decisions can make the playbook easier to repeat correctly.
Premium paid or received is not the same as the larger stock or cash exposure that exercise or assignment can create.
Open interest and volume do not guarantee good liquidity or good execution quality.
Time decay tends to accelerate as expiration approaches, which can change the behaviour of both long and short options.
Short positions may be assigned, and expiring in-the-money options are commonly subject to automatic exercise procedures unless contrary instructions are given through the clearing chain.
Defined-risk spreads still require management near expiry, especially if one leg could remain active while the other is not managed.
Exact expiry procedures, broker cut-offs and product specifications can vary by product and firm.
Verified callouts
Premium, multiplier, and actual cash cost
A quoted option premium is usually stated on a per-share basis, while the contract multiplier converts that quote into actual cash. For a standard U.S. equity option, one contract generally covers 100 shares, so a premium of 2.40 means $240 per contract before fees. Premium paid or received is not the same as the larger notional stock exposure the contract can control.
Liquidity indicators are useful, but not interchangeable
Bid-ask spread is the most immediate signal of likely execution quality, while open interest is only the number of outstanding contracts. Volume and open interest do not guarantee liquidity, and displayed bids and offers matter more to the next execution. Limit orders help control price when visible size is thin or conditions are volatile.
Settlement style changes what expiry can create
American-style options may be exercised before expiry, while European-style options are generally exercisable only on expiration. Some products settle into stock, others into cash, so the same in-the-money outcome can produce either a delivery obligation or a cash settlement amount. Because expiring in-the-money options are commonly subject to automatic exercise procedures and short positions may be assigned, pre-written management rules reduce avoidable expiry risk.
Update log
- OCC, Characteristics and Risks of Standardized Options
- OCC, June 2024 ODD PDF
- FINRA, Options
- FINRA, Trading Options: Understanding Assignment
- Cboe, Equity Options Product Specifications
- Options Industry Council, General Information FAQ
- Options Industry Council, Trade Entry & Execution FAQ
- Options Industry Council, Theta
- Options Industry Council, Options Basics
- Cboe / OIC, The Facts About Options
- OCC, Information memo on exercise-by-exception
- OCC, Rules
- SEC filing discussing implied volatility and realised volatility terminology in options context